Ad-supported plans deliver half of SVOD growth as household budgets tighten

SVOD reaches 28 million services as BVOD, creator content and microdramas compete for viewing time

SYDNEY, AUSTRALIA – Australia’s subscription entertainment market grew by 5 per cent to 57.6 million services in the 12 months to June 2026, according to new research from the Australian emerging technology analyst firm, Telsyte.

The Telsyte Australian Subscription Entertainment Study 2026 found the market is maturing, with growth continues across the three main categories of SVOD (5%), streaming music (6%), and games-related subscriptions (4%).

Ads and deals carry SVOD to 28 million

More affordable ad-supported plans, deals, cross-sector bundles and the inclusion of more sport lifted Subscription Video on Demand (SVOD) services to 28.0 million by June 2026, up 5 per cent year-on-year.

This marks the fourth consecutive year of single-digit growth since the market last expanded by double digits in FY2022. Ad-supported subscriptions climbed 11 per cent to 7.1 million, accounting for 52 per cent of the total net increase, while ad-free subscriptions grew about 3 per cent.

Paid subscriptions increased by 5 per cent over the same period, while non-paying subscriptions rose 17 per cent, driven by free trials and partner offers ranging from telco and utility bundles to rewards redemption. Paid subscriptions account for 94 per cent of the total.

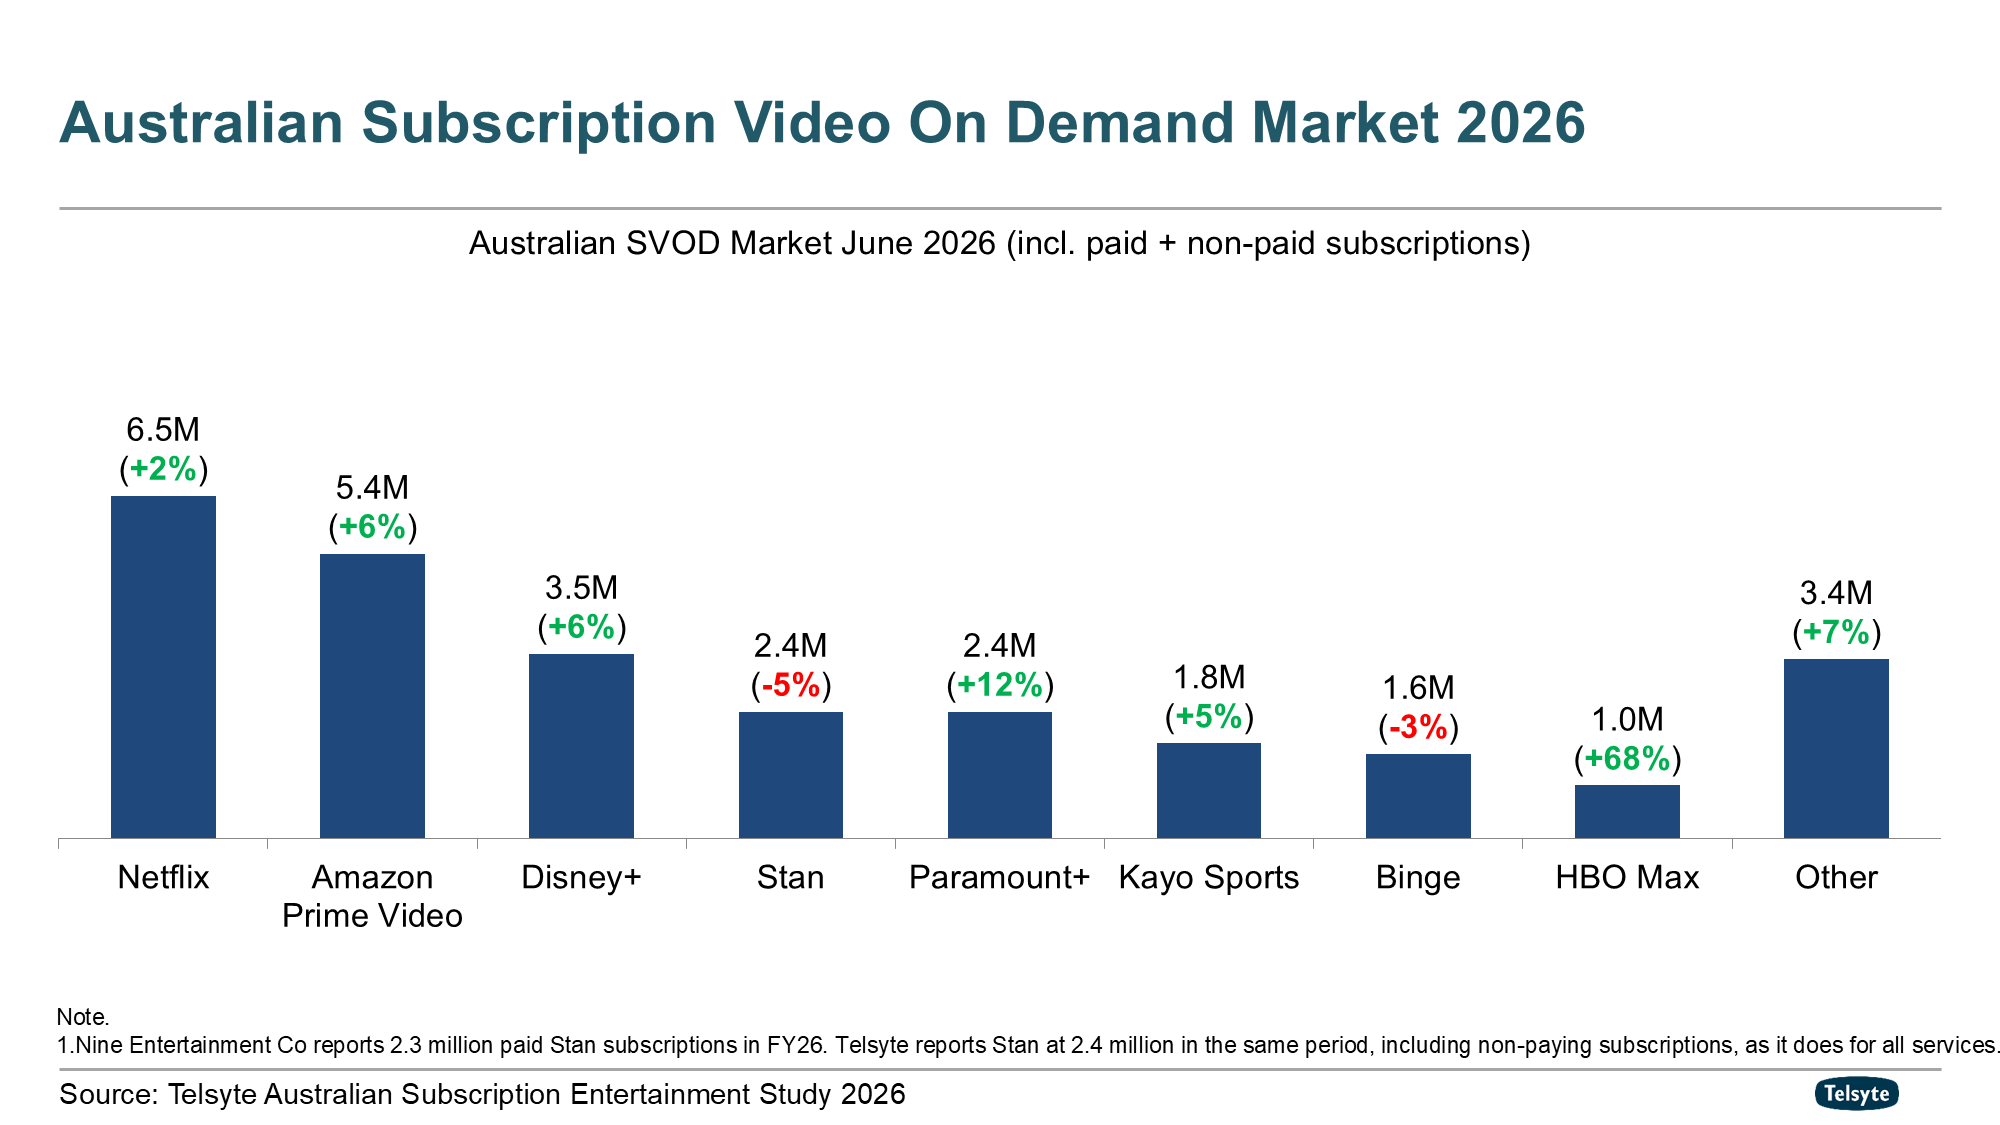
The order of market leaders was unchanged with Netflix (6.5 million) holding the top position, followed by Amazon Prime Video (5.4 million); Disney+ (3.5 million); Stan (2.4 million); Paramount+ (2.4 million); Kayo Sports (1.8 million); Binge (1.6 million); and HBO Max (1.0 million). HBO Max was the fastest-growing major service in FY2026 following its launch in March 2025.

The long tail of services with fewer than one million subscriptions collectively grew by 7 per cent, with genre specialists Crunchyroll (anime) and Hayu (reality) growing fastest.
 

Streaming holds its place in the household budget

Telsyte found the average monthly budget among those willing to pay for streaming video services rose 4 per cent to $43.5, in line with inflation and well below the 18 per cent jump a year earlier, even as six of the top ten SVOD services raised prices during FY2026.

Some 12 per cent of households cut back on SVOD spending in the past year. However, paid SVOD services rank 12th among Telsyte’s 23 tracked areas of reduced household spending, down from 10th a year ago. Dining out and takeaway, clothing and accessories, groceries and holiday spending lead the list.

Most subscribers (71%) notice when a service they pay for raises its price, yet more than a third of Australians (36%) say entertainment subscriptions are among the last things they would cut from their household budget.

Telsyte Principal Analyst Foad Fadaghi says the market is under increasing pressure, with household streaming budgets flat in real terms pushing providers to lean on advertising and deals to sustain growth.

“Cutting streaming services simply does not impact household budgets like bigger ticket items such as whitegoods, travel and eating out,” says Fadaghi.

The wider availability of ad-supported plans is giving consumers more choice within their budgets, with Disney+ adding an ad tier in April 2026. Amazon Prime Video and Netflix hold the largest ad-supported subscriber bases. Half (51%) of SVOD subscribers say what they save on an ad-supported plan is worth putting up with the ads, rising to 58 per cent among those with three or more services.

Deals are also appealing, with around a quarter of SVOD subscribers encountering offers in the past year including cross-sector partnerships spanning telecom, utilities, financial services and other sectors. Most acted on them, securing an average 39 per cent discount for three months.

Some 41 per cent of SVOD subscribers say they rotate between services more than they did a year ago to manage costs, down from 46 per cent in 2025, and subscribing households held steady at 3.3 services on average.

“Ad-supported plans are where subscribers land when budgets tighten. Any price rise from here could see subscribers walk away,” says Telsyte Senior Analyst Alvin Lee.

Creators rival the streamers as microdramas reach one in four Australians

In addition to paid SVOD, free and ad-supported services remain a critical part of Australians’ video entertainment mix.

Telsyte found average weekly video consumption held steady at around 51 hours. Broadcast Video on Demand (BVOD) recorded the largest gain, up 0.9 hours a week, with YouTube also edging up, while SVOD viewing eased 0.6 hours even as SVOD subscriptions grew 5 per cent. Viewing time across other categories was largely unchanged.

Each of the five main BVOD services (7plus, 9Now, 10, ABC iView and SBS On Demand) reached at least 12.9 million viewers over the past year, helped by major events such as the Winter Olympics and the FIFA World Cup.

Free ad-supported streaming TV (FAST) services reached 2.4 million users, up 4 per cent after growing more than 40 per cent the previous year, led by Samsung TV Plus and LG Channels.

Social media video platforms such as YouTube and TikTok continue to attract mainstream audiences, with 18 million Australians watching YouTube. Half of them are doing so daily, drawn mainly by creator-led and user-uploaded videos.

The research found 5.7 million Australians paid for creator ‘member’ subscriptions on platforms such as YouTube, Twitch, X and Patreon in the past 12 months.

“The creator economy in Australia in aggregate has as many paying subscribers as major streaming providers,” says Fadaghi.

Microdramas, an emerging format of short, serialised dramas shot vertically for phone screens with episodes typically running a few minutes, have already reached one in four Australians (26%) in the past 12 months.

Telsyte research found that when Australians have ten minutes to fill, close to half (46%) turn to social media or YouTube. Microdramas extend scripted storytelling into those short phone sessions, a slot long-form video is less suited. Telsyte expects the format to take a growing share of viewing time, as it has overseas.

Sport draws SVOD sign-ups

The increasing inclusion of sport is also driving growth, with more than one in five (23%) subscribers to Australia’s top SVOD services (excluding dedicated sport service Kayo) citing sport as a key reason for signing up, as general entertainment services add more live sport to their line-ups.

The study found three in five (61%) Australians say major national sporting events should remain free to watch, even if other sport content is paid, in line with Australia’s anti-siphoning rules.

Half (50%) of SVOD subscribers say it is important for streaming services to carry content that represents Australian stories, voices, culture and values, down from 58 per cent in 2025, as major streaming services begin meeting new local content investment obligations. Telsyte believes the cost of living and rising subscription prices might have weighed on this result.

Even so, more SVOD subscribers having seen Australian-related programming than other content, with working and everyday Australian life (40%) and regional and remote Australia (31%) lead the stories subscribers most want to see on screen.

Streaming music subscriptions steady on

Streaming music reached 20 million subscriptions at the end of June 2026, up 6 per cent from previous year, supported by population growth and bundled access. Half (50%) of music streamers say access to their services are essential, up from 44 per cent a year ago.

Spotify, Google (including YouTube Music and YouTube Premium listeners for music) and Apple Music remain Australia’s top streaming music providers.

Bundled play lifts games-related subscriptions as hardware costs bite

Australians held 10 million games-related subscriptions at the end of June 2026, up 4 per cent year-on-year, driven by Netflix Games as it expands from mobile to TV and computer. Excluding Netflix Games, subscriptions declined 2 per cent as price rises for subscriptions and gaming hardware weighed on demand.

For further information on the study or media enquiries contact:

Foad Fadaghi
Managing Director
Tel: 1800 313 142
Email: ffadaghi@telsyte.com.au

Alvin Lee
Senior Analyst
Tel: 1800 313 142
Email: alee@telsyte.com.au

The Telsyte Australian Subscription Entertainment Study 2026 is a comprehensive study which provides subscribers with:

  • Market sizing and forecasts of the Australian entertainment subscriptions market, including video, music and games

  • Insights into consumer attitudes and technology adoption trends

  • Uptake, intention and detailed analysis of

    • Video services including: SVOD, pay TV/IPTV, BVOD and FAST services

    • Streaming audio-related services

    • Games-related subscription services

  • Service and content consumption preferences

  • Insights into the future of entertainment subscription services in Australia.

In preparing this study, Telsyte used:

  • An online survey conducted in August and September 2026 with a representative sample of 1,025 respondents, 16 years and older.

  • An online survey conducted in April and May 2026 with a representative sample of 2,023 respondents, 16 years and older.

  • Interviews conducted with executives from SVOD, Pay TV/IPTV and video game service providers, content providers, funding agencies and hardware manufacturers.

  • Financial reports released by service providers and media companies.

    On-going monitoring of local and global market trends.

Editor’s note:

  • Telsyte’s measurement includes both paid and non-paying subscriptions.

  • Where a subscription bundles services across categories, Telsyte measures each service as a subset of the parent subscription, based on subscribers’ self-reported use (for example, Amazon Prime Video and Amazon Music within Amazon Prime, and Netflix Games within Netflix). As a result, category figures for subscription video, music and games do not add up to the market total, in which each subscription is counted only once.

  • Nine Entertainment Co reports 2.3 million paid Stan subscriptions in FY2026. Telsyte reports Stan at 2.4 million in the same period, including non-paying subscriptions, as it does for all services.

  • Stan launched its ad-supported tier in August 2026; it is not included in the FY2026 ad-supported subscription measurement.

  • Telsyte actively monitors the SVOD services market, including over 40 SVOD services. Other examples include Apple TV+, BritBox, beIN Sports, Crunchyroll, Foxtel Now, Hayu, NBA League Pass and etc.

  • The measure is the number of subscriptions at the end of June 2026 (snapshot), not usage/utilisation. Content releases will influence the number of subscriptions when measured at different points in time.

  • Telsyte measures the hours that consumers spend on consuming all types of video content. Examples include FTA TV, SVOD, Pay TV, social media videos, BVOD, FAST services etc.

  • Examples of FAST services include Samsung TV Plus, LG Channels and Plex.

  • Payment made to directly support individual creators excludes adult content.

  • Microdramas are short, serialised dramas, typically filmed in vertical format with episodes of a few minutes or less, distributed through social platforms and dedicated apps such as ReelShort and DramaBox. Local media companies have begun testing short vertical formats, including Nine’s microreality series Flex.

About Telsyte

Telsyte is Australia’s leading emerging technology analyst firm. Telsyte analysts deliver market research, insights and advisory into enterprise and consumer technologies. Telsyte is an independent business unit of DXC Technology. For more information visit www.telsyte.com.au

The material in this article is copyright protected and not intended to be altered, copied, distributed or used for any commercial or non-commercial purpose, except for news reporting, comment, criticism, teaching and scholarship.
Australia's smart home market soars on battery boom

Market set to top $11 billion in 2026

SYDNEY, AUSTRALIA – Australia's smart home market is forecast to exceed $11 billion in 2026, after more than doubling to $7.7 billion in 2025, as government battery incentives and rising energy costs drive demand for storage and energy management, according to new research from the Australian emerging technology analyst firm, Telsyte.

The Telsyte Australian Smart Home Market Study 2025-2029 found smart home adoption continues to mature, with most (86%) Australian households owning at least one smart home product as of June 2026, up 10 percentage points since 2024. Adoption rose across the energy, security and lifestyle segments, with energy products, smart appliances and smart security cameras driving the increase.

Smart home budgets climb despite financial pressure

Households with an allocated smart home budget increased from 44 per cent to 71 per cent over two years. Among those, the average budget rose by over $1,300 to more than $3,500 in 2026. Growth is concentrated among households budgeting above $1,000, reflecting higher costs and the larger investment required for energy management and home improvement projects.

The study found Australian households are committing to that spending under growing pressure, with 58 per cent feeling more financially stretched than a year earlier and 69 per cent actively working to lift income or reduce expenses. Saving money and managing rising costs remains the top smart home priority, followed by energy management.

Batteries account for two thirds of market revenue

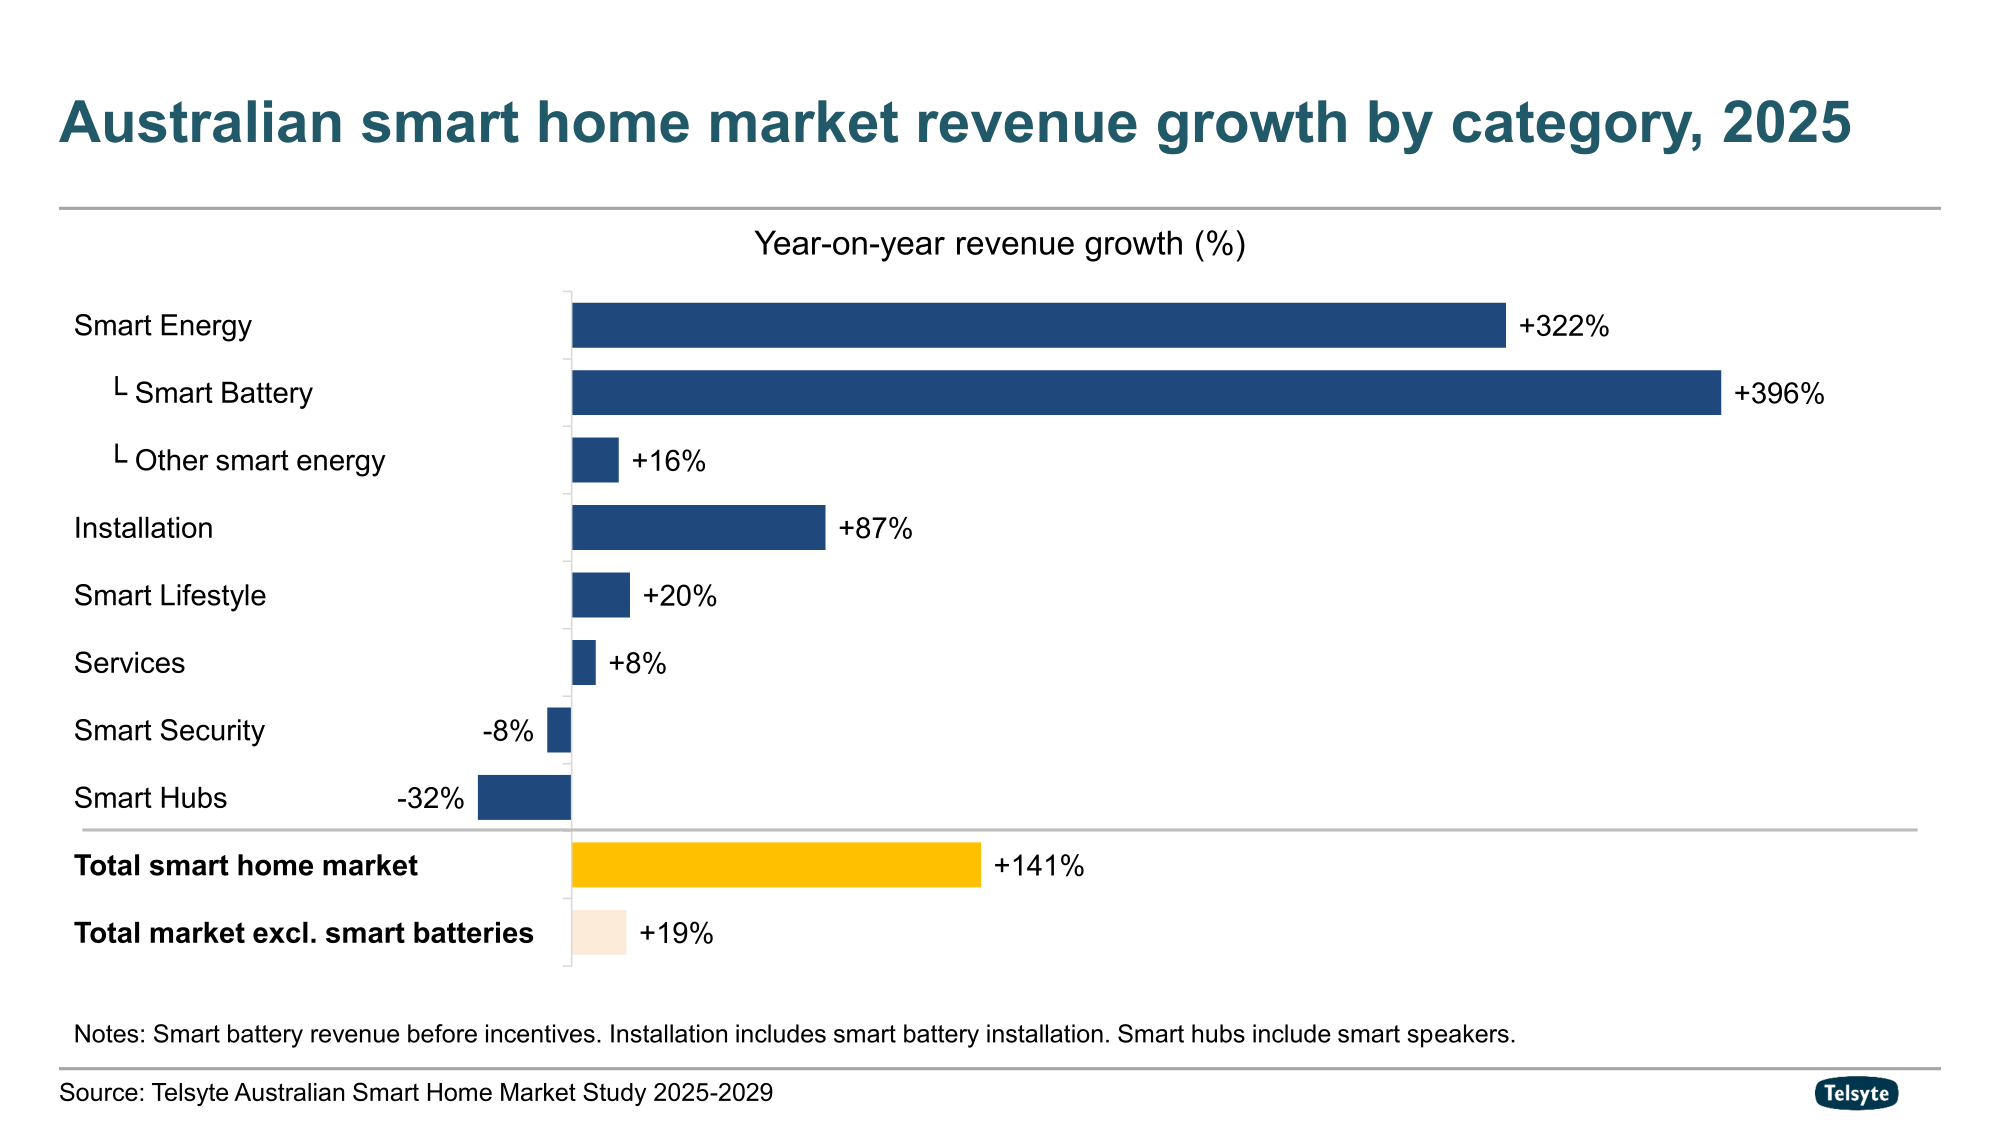
Smart battery systems contributed two thirds of smart home market revenue in 2025 following the launch of the Federal Government’s Cheaper Home Batteries Program, with battery revenue up 396 per cent year-on-year. Excluding smart batteries, the market still grew 19 per cent year-on-year in 2025.


About two in five Australian homes have rooftop solar, and the program has recorded rapid adoption of battery storage in just over 12 months. Telsyte’s research found more than a third of households without solar or battery storage are interested in installing them, indicating the shift towards larger budgets has further potential.

Telsyte expects the battery share to peak in 2026 before moderating to just over half by 2029 under the program's new tiered structure.

More solar power plugging into more EVs

Australia’s expanding solar and battery infrastructure is primed for more electric vehicles (EVs), with Telsyte research finding 37 per cent of non-EV owners would still consider buying one even if fuel prices returned to normal levels.

“Many solar powered homes are taking the next step with batteries and EVs,” Telsyte Managing Director, Foad Fadaghi, says.

Telsyte estimates around half a million EVs will be on Australian roads by the end of 2026, complementing smart battery systems and driving further demand for EV wall chargers and household energy management.

Among solar or battery adopters, 61 per cent are interested in an energy management service, as households accumulate generation, storage, a vehicle charger and a time-of-use tariff that all need to be scheduled against each other. Interest in virtual power plants is also high, reaching 63 per cent among battery owners.

Telsyte also expects the Government's offers like Solar Sharer Offer and Midday Power saver will draw more renters and apartment dwellers into the smart energy market.

Telsyte believes household energy management is becoming the coordinating layer of the smart home, and a sizeable subscription revenue opportunity beyond hardware sales.

Amid the growing complexity, professional installation services remain in high demand, with smart home installation revenue growing 87 per cent year-on-year in 2025, driven by battery installations.

Professional installers' advice is highly valued by 79 per cent of Australians actively looking for ways to make their home smarter, making the trades an increasingly influential channel for product selection.

New smart spaces bring together emerging tech

With smart home products now in most households, consumer attention is turning to specific spaces and outcomes.

The areas Australians most plan to improve with smart home technology are entertainment areas, outdoor living spaces and home offices, while connected products are increasingly used to support wellness, monitoring and comfort as the population ages.

Telsyte forecasts the smart lifestyle segment to grow at 21 per cent CAGR to 2029, the highest of any segment, driven by the growing availability of smart appliances and household robots, including robotic vacuums, window cleaners and lawn mowers.

Smart security adoption continues to rise, led by smart cameras and video doorbells, but revenue declined 8 per cent in 2025 amid increased price competition and demand for products that meet basic monitoring needs with limited smart or AI-enhanced features. Telsyte expects more advanced AI features such as recognising specific people, pets and objects to become the main way vendors compete beyond price, with local storage of recordings helping to address privacy concerns.

AI and user experience the next smart home battleground

As appliance and device makers extend connected features across entire product ranges, from cooking and cleaning to climate, security and energy, Telsyte expects AI-enhanced smart living to appeal to households seeking hyper-personalisation and improved everyday living.

Competition will shift from device specifications to the quality of the experience that ties products together.

Interoperability remains a gap. Among smart home adopters, 67 per cent have had difficulty getting their devices to work together, while only one in seven Australians are currently aware of Matter, the cross-brand standard designed to address it.

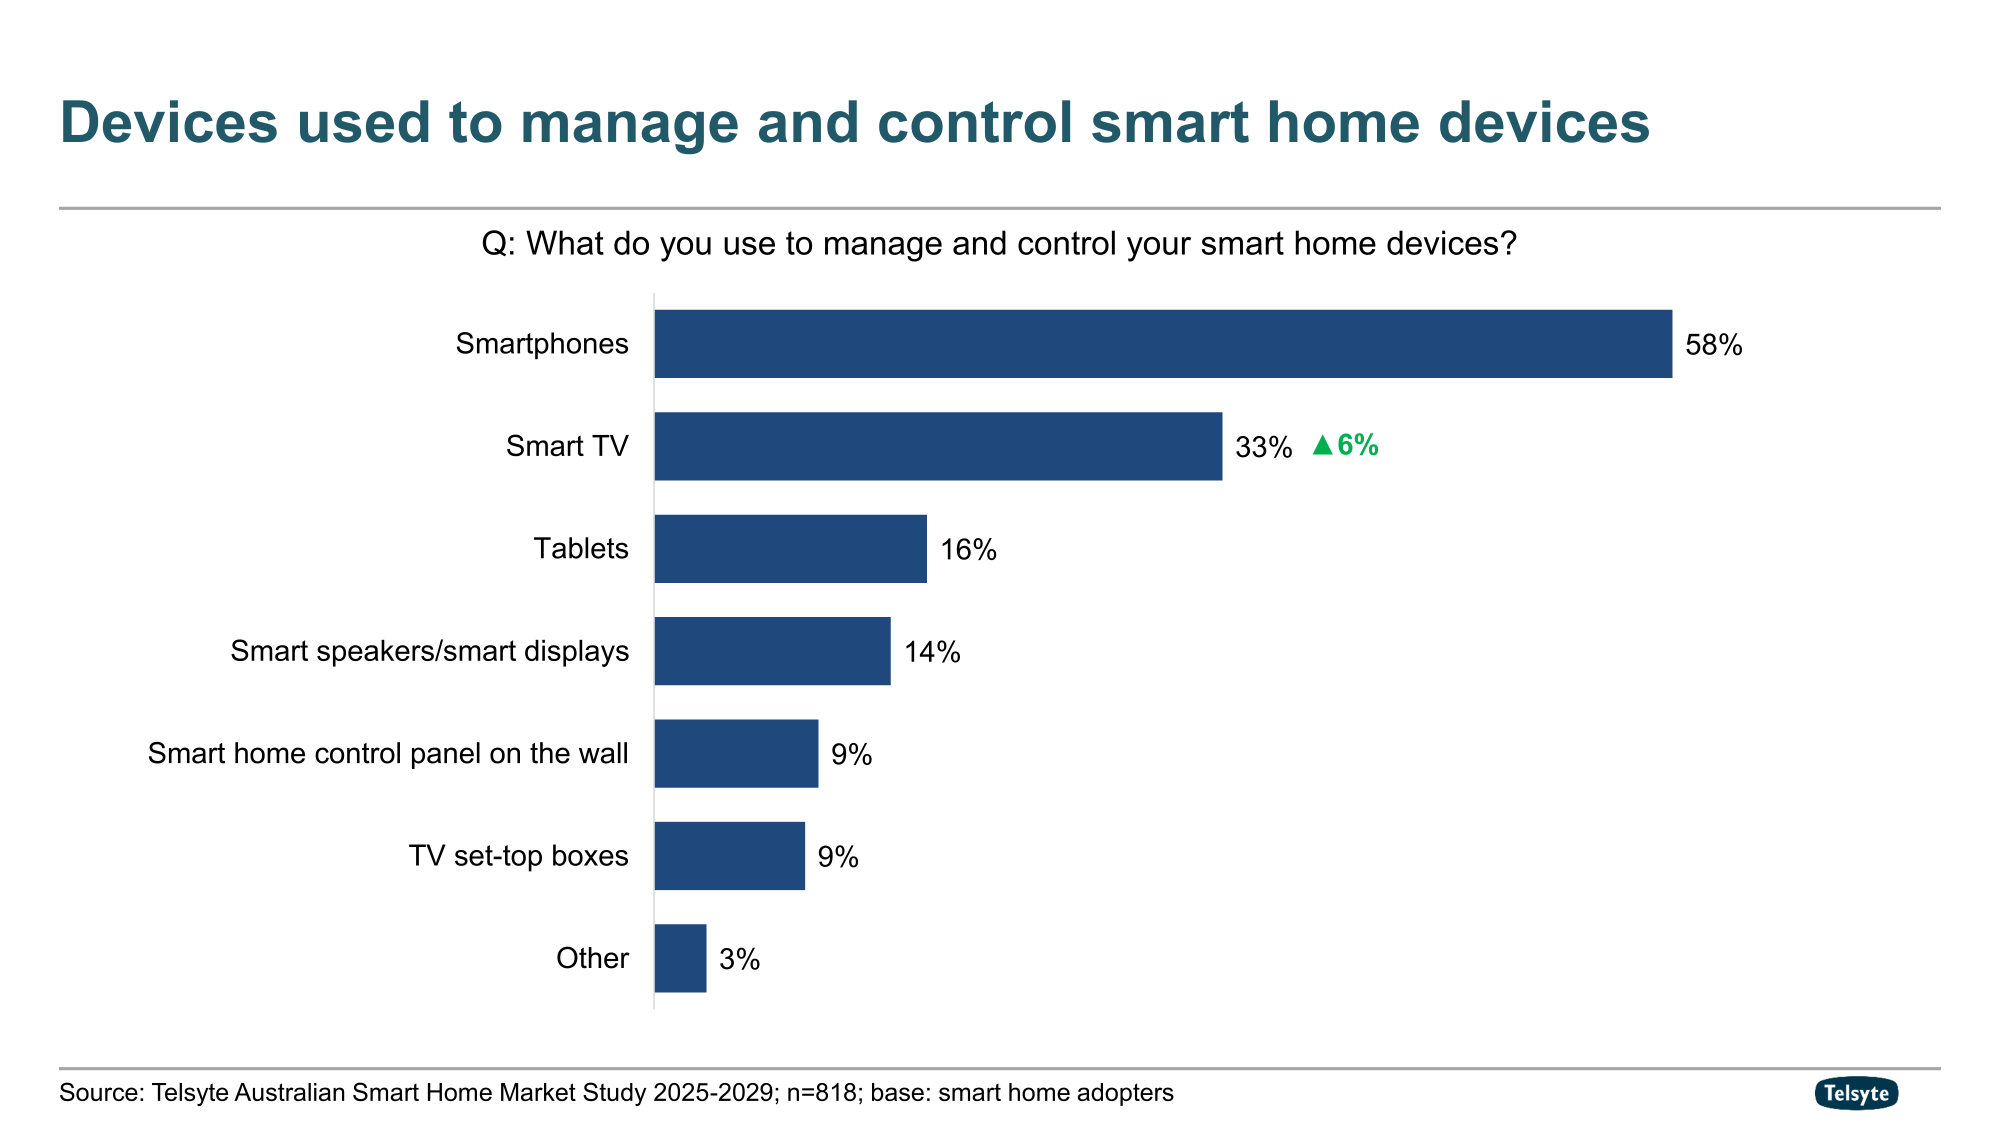
Smartphones remain the dominant smart home controller, used by 58 per cent of smart home users, followed by smart TVs (33%), tablets (16%) and smart speakers and displays (14%).

Revenue from smart hubs, including smart speakers, fell 32 per cent in 2025. Fewer households replaced existing smart speakers, and more smart home products now connect directly via Wi-Fi and apps, reducing the need for standalone hubs. However, Telsyte sees an opportunity for a new generation of shared household interfaces that use more advanced AI to recognise who is in the room and adjust controls, routines and settings to suit that person, beyond the personal smartphone. Apple’s anticipated smart home hub could help revive demand for the category, challenging Google and Amazon, which lead the installed base of smart speakers in Australian homes, with Apple third.


The study found 70 per cent of Australians believe AI could manage a smart home better than they can, up from 58 per cent in 2024, particularly for security, energy, diagnostics and comfort applications.

However, more than three in five would feel uncomfortable if AI made decisions in their home without their prior knowledge, and a similar rate are concerned about AI systems making mistakes.

“Households will hand AI the keys when privacy and security safeguards are in place,” Telsyte Senior Analyst, Alvin Lee, says

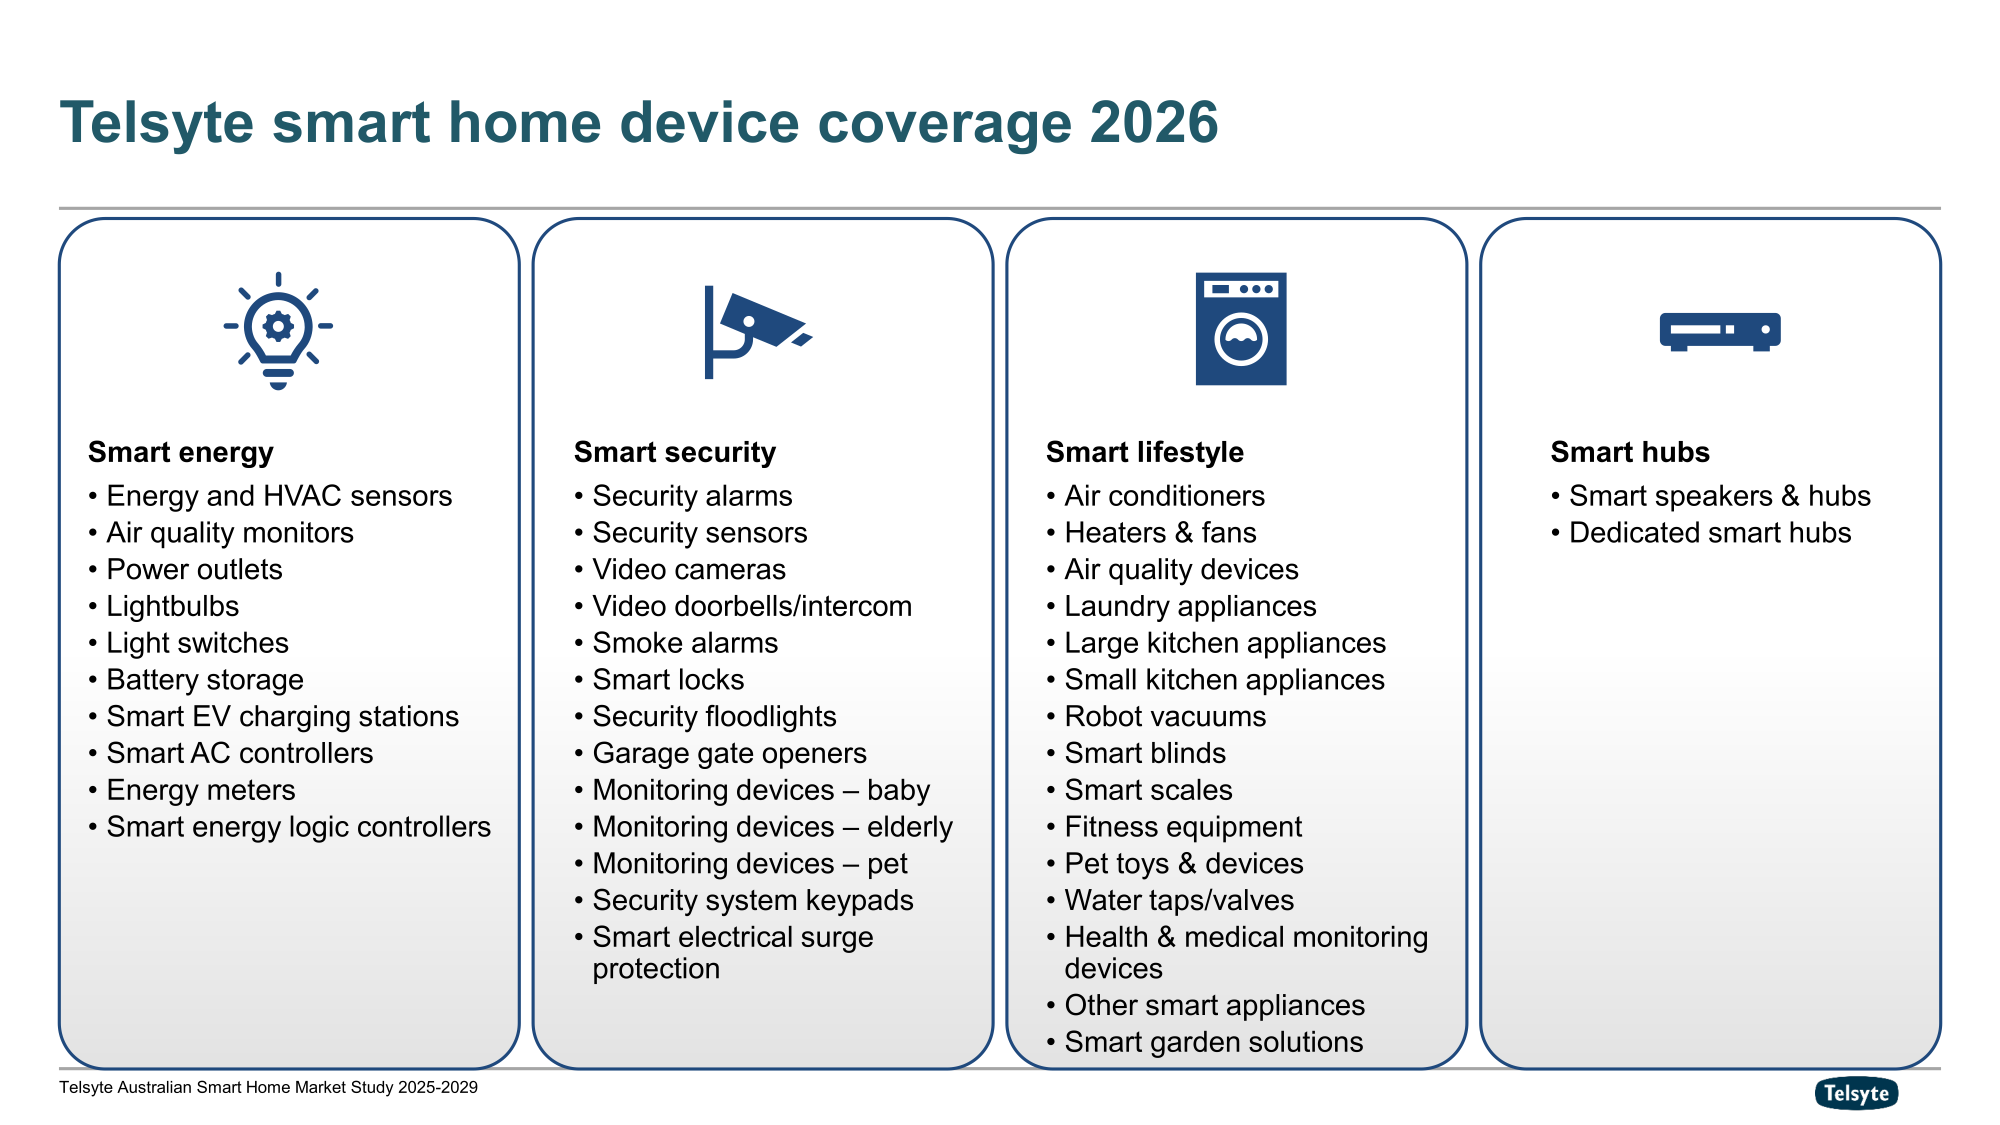
The taxonomy of Telsyte's Australian Smart Home Market Study 2025-2029:

Smart home segments covered:


For further information on the study or media enquiries contact:

Foad Fadaghi
Managing Director
Tel: 1800 313 142
Email: ffadaghi@telsyte.com.au

Alvin Lee
Senior Analyst
Tel: 1800 313 142
Email: alee@telsyte.com.au

The Telsyte Australian Smart Home Market Study 2025-2029 is a comprehensive study which provides subscribers with:

  • Market sizing and forecasts of the Australian smart home market by detailed segments including services and installation revenues

  • Insights into consumer attitudes and technology adoption trends

  • Analysis of vendor strategies and key growth segments

  • Smart home user profiles, including adopters, those on the verge of adopting and those not yet interested, as well as by their range of budgets.

  • Analysis of the smart home ecosystems

  • Analysis of retail and online channels and their importance to smart home products

  • Insights into where consumers begin their smart home journey and key market drivers expected to drive rapid adoption in different segments.

In preparing this study, Telsyte used:

  • Telsyte’s Smart Home survey conducted during May and June 2026 with a representative sample of 1,012 respondents, 16 years and older.

  • Interviews conducted with executives from service providers, network operators, manufacturers, retailers, financial analysts and channel partners.

  • Financial reports released by manufacturers, retailers and service providers.

  • Ongoing monitoring of local and global market and vendor trends.

Editor’s note:

  • Smart battery revenue is calculated before any incentives are applied, including those under the Federal Government's Cheaper Home Batteries Program.

  • Electric vehicles are not included in Telsyte’s smart home market revenue, but smart EV wall chargers are included.

  • From 1 May 2026, the Cheaper Home Batteries Program moved to a tiered structure, with the strongest rebate applying to the first 14kWh of capacity and reducing above that. Telsyte expects this to moderate average system size rather than the appetite for storage.

  • The Solar Sharer Offer is a regulated electricity offer available to eligible households with a smart meter in New South Wales, South Australia and south-east Queensland. Free electricity is capped at 24kWh per day.

  • Victoria's Midday Power Saver offers free electricity from 11am to 2pm daily to households with a smart meter that opt in through their retailer.

  • Top home battery brands installed in Australian homes include Alpha ESS, BYD, LG, Sigenergy, Sungrow and Tesla (in alphabetical order).

About Telsyte

Telsyte is Australia’s leading emerging technology analyst firm. Telsyte analysts deliver market research, insights and advisory into enterprise and consumer technologies. Telsyte is an independent business unit of DXC Technology. For more information visit www.telsyte.com.au

The material in this article is copyright protected and not intended to be altered, copied, distributed or used for any commercial or non-commercial purpose, except for news reporting, comment, criticism, teaching and scholarship.
Premium devices now command more than half of Australian smartphone sales

Apple nears OS parity as component costs set up second-half price rises.

SYDNEY, AUSTRALIA – More than half (56%) of all smartphones sold in Australia in the first half of 2026 were premium devices priced above $1,000, with more than one in five costing above $2,000 (ultra-premium), according to new research from the Australian emerging technology analyst firm, Telsyte.

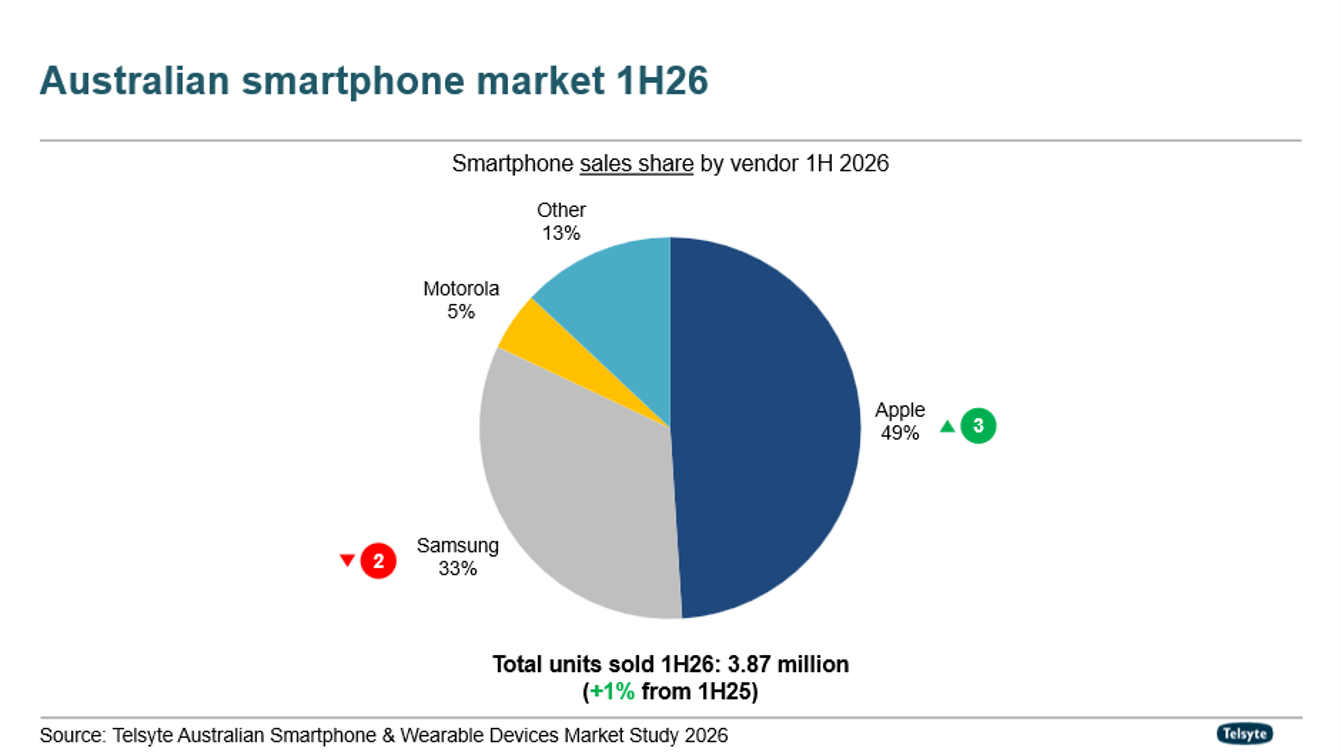
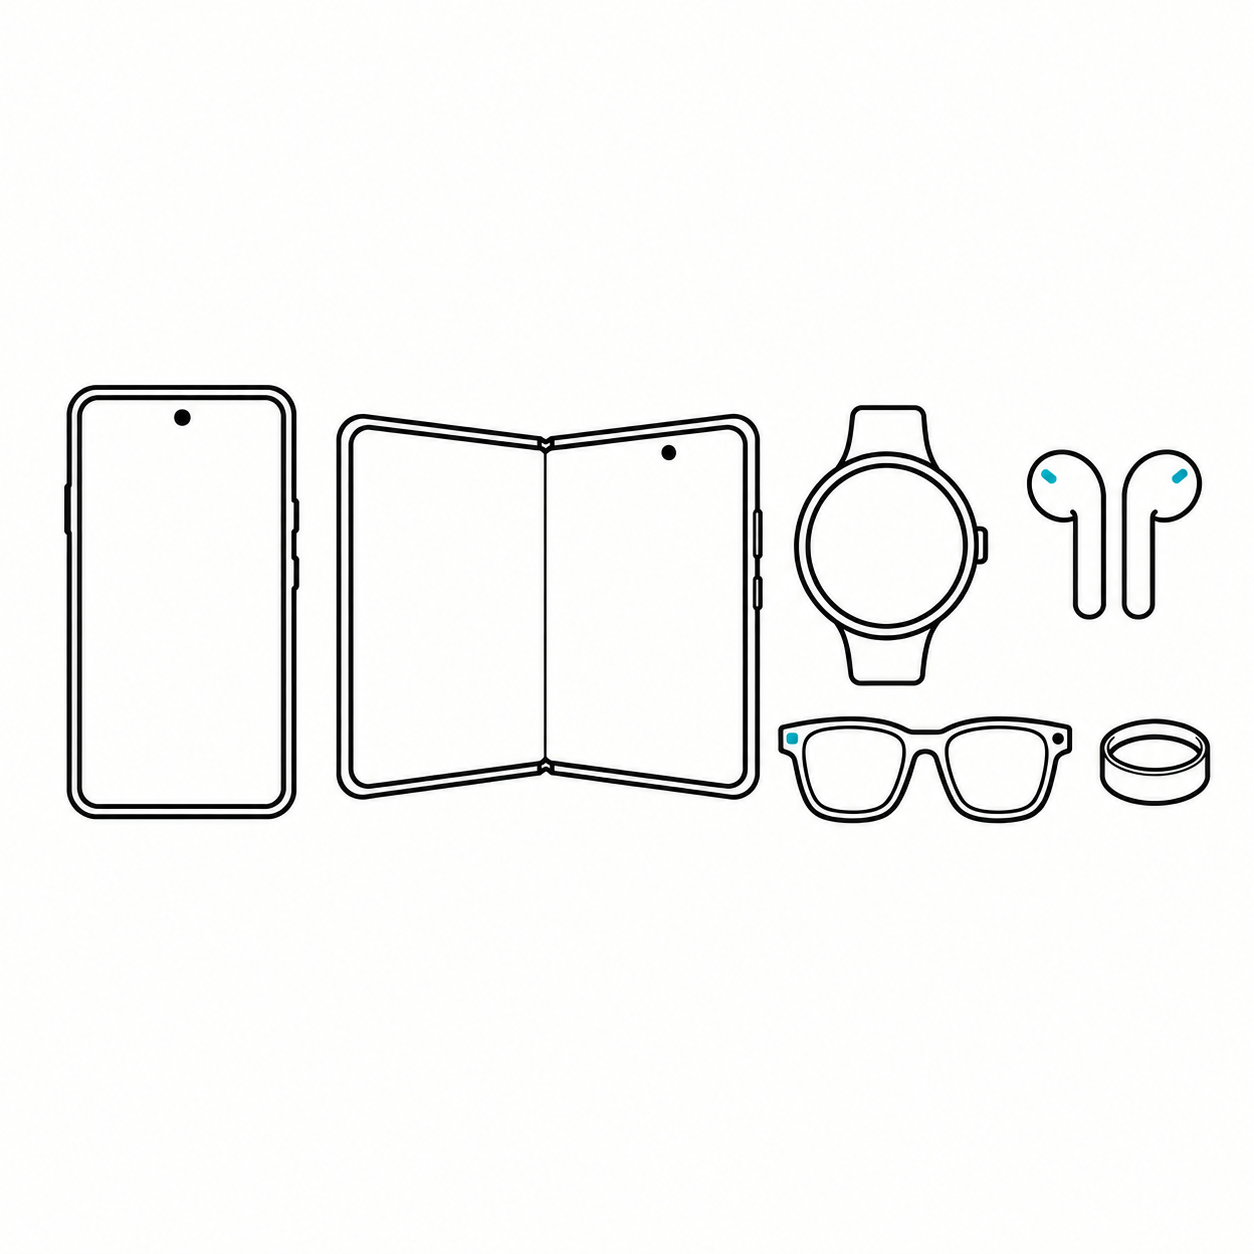
The Telsyte Australian Smartphone & Wearable Devices Market Study 2026 found total smartphone sales reached 3.87 million units in the first half, up one per cent year-on-year, with the premium segment adding 10 percentage points of share over two years.

Apple accounted for almost half (49.4%) of first-half sales, bringing it within reach of Android. iPhone sales rose seven per cent while Android volumes fell five per cent year-on-year, with the weakness concentrated in sub-premium handsets and premium Android volumes still growing.

Telsyte believes some iPhone buyers have brought upgrades forward amid reported expectations of component-driven price increases. Apple, Samsung and Motorola are the top three vendors, with Motorola and Oppo separated by a slim margin having traded third and fourth positions several times over the past two years.


The first-half result was also driven by inventory brought into the market ahead of rising memory and component costs, which has kept retail pricing broadly stable and insulated buyers from underlying movement. Telsyte believes that buffer is thinning, and that stock replenished at current prices will bring more widespread increases through the second half of 2026.

Telsyte forecasts 8.4 million smartphones will be sold in Australia in 2026, down three per cent year-on-year, with the decline weighted towards the second half as memory-driven cost increases are reflected more broadly across the device range. Demand is expected to remain concentrated in the premium tier, supported by consumer intent to future-proof the next device and treat it as a long-term investment.

Australia's average smartphone replacement cycle has shortened to 3.4 years, down from a peak of 3.9 years at the end of 2023. The decline is most pronounced among Android users, whose cycle has compressed by 0.7 years compared with 0.4 years among iPhone users, reflecting the concentrated impact of the 2024 3G network closure on lower-cost handsets.

Budget users now hold their devices twice as long as ultra-premium buyers, concentrating the most commercially active upgraders at the top of the market. That segment is the primary audience for premium devices, on-device AI and next-generation form factors such as foldables. Apple and Samsung lead the premium and ultra-premium tiers, where competition from brands including Oppo, Google, Motorola, Nothing and Honor is intensifying as more players push upmarket.

Despite persistent cost-of-living pressure and the increasing popularity of refurbished phones, Telsyte research found 85 per cent still prefer to purchase a new device, managing affordability by choosing last year’s flagship models or switching brands.

Over 11 million Australians are using device-integrated AI features on their smartphones, from writing assistance and photo editing to live translation, making the smartphone the most widely adopted AI device in the country. Only one in three, however, say their next smartphone must include advanced AI features, with battery life, performance and storage remaining the dominant considerations. While 58 per cent are willing to allow AI access to selected apps and information on their device, only 21 per cent are comfortable with AI suggesting actions without being asked.

Foldables gaining traction, an Apple entry would ignite foldable market

The study found foldable smartphones now account for approximately five per cent of annual smartphone sales, but are yet to cross into the mainstream. Telsyte believes an Apple foldable (expected in  2026) will be the single largest catalyst for the category.

Consumer appetite for an Apple foldable is high with one third of iPhone users would consider a foldable iPhone, rising to nearly half (46%) among users of the iPhone 15, 16 and 17 Pro series. One in six (17%) of those Pro series users would pay $3,000 or more, placing early demand squarely in the segment that already spends the most.

If Apple launches a foldable iPhone in 2026, Telsyte believes it could become the second largest foldable vendor in Australia within its first year, assuming supply is not constrained.

Telsyte estimates a price premium of 30 to 40 per cent above the iPhone Pro Max, placing the device in the ultra-premium tier, the strongest growth segment in the market today. Samsung is expected to retain the lead with its broadest line-up yet, including a newly designed passport-style Galaxy Z Fold 8.

iPhone users are evenly split between the larger, taller book-fold style and the more compact flip, against a clearer preference for the book-fold format among Android users (58%).

“Despite the potential lofty prices, a new foldable iPhone could finally propel the category into the mainstream” Telsyte principal analyst Foad Fadaghi says.

Ecosystem wearables deepen as smart glasses emerge

More than 800,000 smart wrist wearables were sold in the first half of 2026, down eight per cent year-on-year as the category matures and budgets tighten. Apple, Samsung and Garmin lead, with smartwatches accounting for more than 70 per cent of sales. Demand is now driven by ecosystem lock-in, fitness and health sensing upgrades and deeper assistant integration.

Smart ring adoption remains embryonic, with fewer than five per cent of Australians owning one and Samsung leading the category. Interest sits at just over a quarter (29%), reflecting the fitness and health tracking wrist wearables already deliver to a far larger installed base.

Smart hearables sales reached more than 1.2 million units over the same period, up 16 per cent year-on-year, driven by new product releases, bundling and a more affordable upgrade path than other personal devices. Close to half (48%) of users wear their devices daily and more than a quarter use voice features every day, making hearables a natural companion to on-device AI.

Smart glasses adoption is equally embryonic, though interest runs well ahead of smart rings, with two thirds (66%) saying they would consider one. More than two thirds of current owners wear Meta's AI glasses, including Ray-Ban and Oakley branded models. The most sought-after features are hands-free photo and video capture (28%), real-time information about what they see (23%) and reduced phone usage (22%).

"AI is moving from something Australians open to something they wear," says Telsyte Senior Analyst Alvin Lee.

Telsyte expects sub-$100 glasses and premium ecosystem entrants to broaden the category over the next twelve months, though social and privacy concerns are likely to persist. Nearly half (47%) of Australians say they would feel self-conscious wearing smart glasses in public, and only 30 per cent are comfortable with people around them regularly wearing camera-equipped smart glasses.

For further information on the study or media enquiries contact:

Foad Fadaghi
Managing Director
Tel: 1800 313 142
Email: ffadaghi@telsyte.com.au

Alvin Lee
Senior Analyst
Tel: 1800 313 142
Email: alee@telsyte.com.au

The Telsyte Australian Smartphone & Wearable Devices Market Study 2026 is a comprehensive study that provides subscribers with:

  • Smartphone market sizing estimates, platform and vendor market shares and forecasts

  • Smart wrist-based wearables market sizing estimates, platform and vendor market shares and forecasts

  • Smart hearables market sizing estimates, platform and vendor market shares and forecasts

  • End user trends across devices, application usage, platforms and operators

  • Purchase intentions and acquisition channels

  • Strategic analysis of recent market trends and developments

In preparing this study, Telsyte used:

  • An online survey conducted in April and May 2026 with a representative sample of 2,023 respondents, 16 years and older.

  • Interviews conducted with executives from service providers, network operators, manufacturers, retailers, financial analysts and channel partners.

  • Financial reports released by service providers, manufacturers and retailers.

  • On-going monitoring of local and global market and vendor trends.

  • Analyst reviews of leading smartphone and wearable devices.

Telsyte measures smart wearables as:

  • Smart wrist wearables: worn on a user’s wrist typically paired and controlled via a smartphone. Examples include products from Apple, Fitbit, Fossil, Garmin, Google, Huawei, Oppo, Samsung, Polar, Ryze, SPACETALK, Withings and others.

  • Smart hearables: smart earbuds and headphones that support digital assistant and typically paired with a smartphone. Examples include Apple Airpods, Samsung Galaxy Buds, Google Pixel Buds, Oppo Enco Clip2, JBL Reflect Flow Pro+, Jabra Elite, Bose QuietComfort® 45, and Sony LinkBuds.

Telsyte covers smartphones from Apple, ASUS, CAT®, Google, HMD, Honor, Motorola, Nokia, Nothing, Opel, OPPO, Samsung, TCL, Xiaomi, ZTE and others.

Editor’s note:

Telsyte's replacement cycle is calculated from the gap between each respondent's two most recent smartphone purchases, reflecting completed replacement behaviour rather than stated forward intent.

Telsyte measures sales of devices (“sell out”), not shipments or sales to retailers or carriers (sometimes called “sell-in”). Telsyte believes this is a more accurate measure of performance of products in a marketplace. Telsyte does not rely on disclosure from vendors or general assumptions made for large multinational companies that do not release local market data. Telsyte uses a comprehensive methodology that includes surveys of consumers, discussions with vendors, carriers and their partners, retailers, and financial analysts. In addition, public financial results from manufacturers and carriers are used. Telsyte tests a wide range of products in real life usage scenarios and conducts satisfaction and repeat purchase surveys with large and representative samples of Australian smart device users. Telsyte is a pioneer in measuring and reporting smartphone sales in Australia and has been providing insights on mobile technologies since 2006.

Device-integrated AI refers to artificial intelligence capabilities built directly into consumer devices. Examples include Apple Intelligence, Samsung Galaxy AI, Gemini on Google Pixel devices, Moto AI and Oppo AI.

About Telsyte

Telsyte is Australia’s leading emerging technology analyst firm. Telsyte analysts deliver market research, insights and advisory into enterprise and consumer technologies. Telsyte is an independent business unit of DXC Technology. For more information visit www.telsyte.com.au

The material in this article is copyright protected and not intended to be altered, copied, distributed or used for any commercial or non-commercial purpose, except for news reporting, comment, criticism, teaching and scholarship.
Four in five AI users now engage monthly as Australia’s user base surges past 17 million

Rapid adoption meets rising caution as AI advertising tests consumer trust

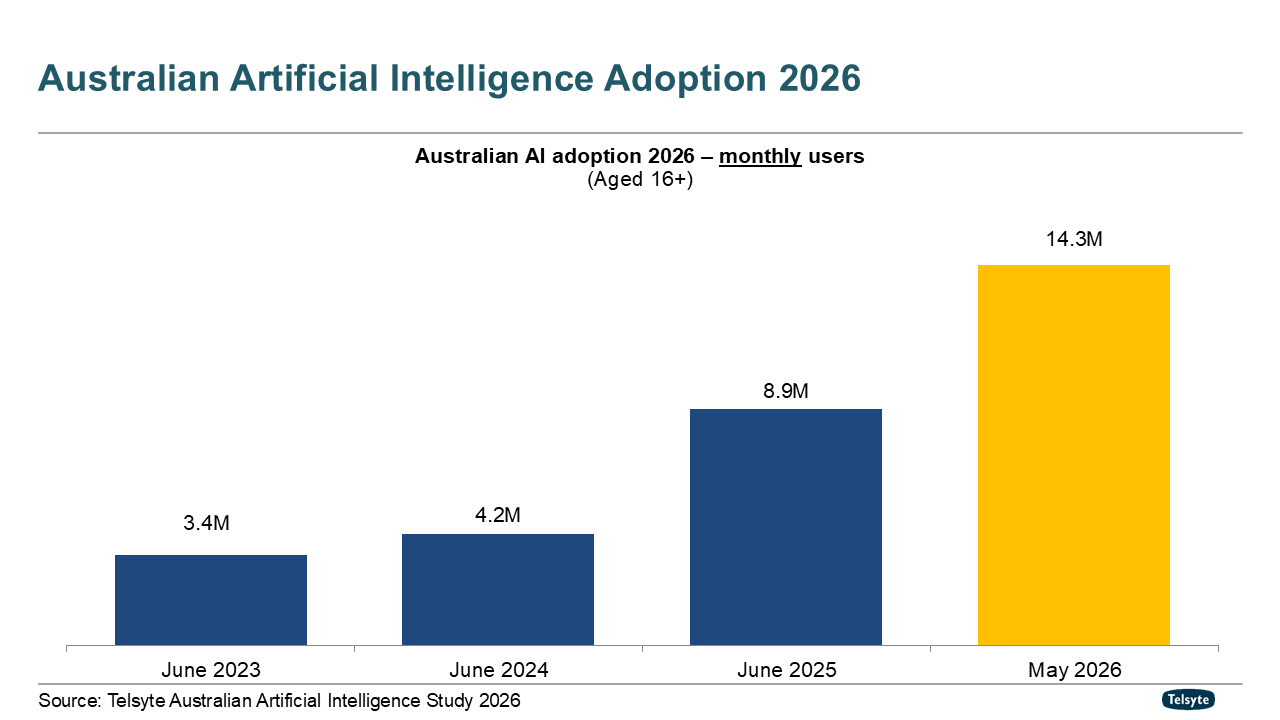
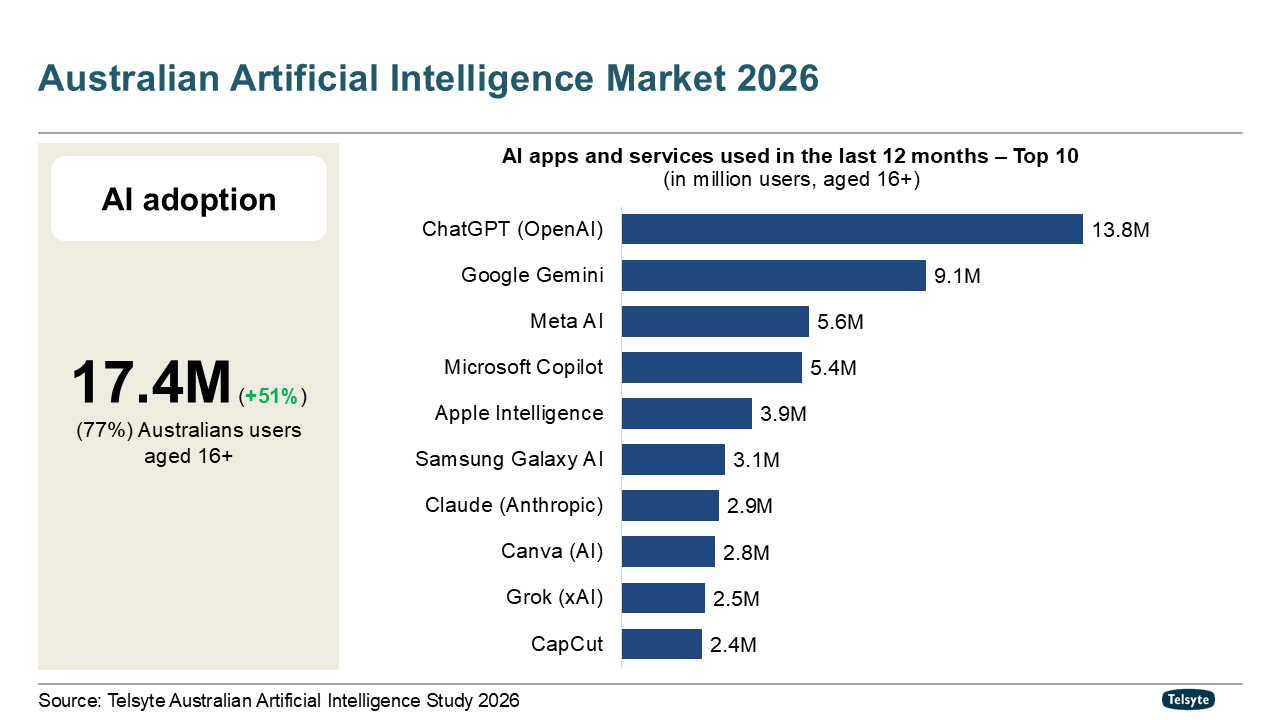
SYDNEY, AUSTRALIA – Artificial intelligence has become part of everyday life for 17.4 million Australians (77% of the 16+ population), as the national user base grew by more than 6 million from June 2025 to May 2026, according to new research from Australian emerging technology analyst firm Telsyte.

The Telsyte Australian Artificial Intelligence Study 2026 found engagement has deepened sharply alongside adoption. Of the AI user base, four in five (14.3 million) engaged with AI at least monthly, up 61 per cent year-on-year – including 5.2 million who now use it every day, a 160 per cent surge from approximately 2 million in June 2025.

More than a third (35%) of users say they are using AI significantly more than a year ago, and nearly half (48%) report improved proficiency with AI tools over the same period.


ChatGPT leads as the competitive field widens

ChatGPT retains dominant market position with 13.8 million users, followed by Google Gemini (9.1 million), Meta AI (5.6 million) and Microsoft Copilot (5.4 million). The top 10 is completed by Apple Intelligence (3.9 million), Samsung Galaxy AI (3.1 million), Claude (2.9 million), Canva AI (2.8 million), Grok (2.5 million) and CapCut (2.4 million).

Typing remains the dominant mode of AI interaction at 80 per cent compared with 20 per cent using voice, a gap Telsyte believes points to potentially significant runway for voice-driven AI experiences in smart home and in-vehicle environments (e.g. Android Auto, Apple CarPlay and Grok on newer Tesla models). 

More than one in five AI users now use five or more services, a figure that nearly doubles among daily users. Telsyte believes service rotation is increasingly driven by use cases and free-tier limits, with standalone AI services facing more loyalty risk than those anchored within established platform ecosystems.


Search goes agentic as trust and advertising pressure converge

While AI is growing rapidly, it is doing so against a backdrop of consumer anxiety about pace and a foundational trust deficit that the industry has yet to resolve. The study finds 62 per cent of Australians feel technology is changing faster than they can keep up with, while just 35 per cent trust technology companies to use their data responsibly. These are foundational constraints that now directly bear on how AI providers monetise their growth.

The majority of AI users remain on free tiers and advertising is emerging as a way for AI service providers to generate revenue, with OpenAI already testing ads within ChatGPT in Australia and the United States.

Australians are broadly open to the concept, as 70 per cent would opt for a free, ad-supported service over a paid, ad-free alternative - yet only 27 per cent are comfortable seeing ads within AI-generated answers, and more than half (52 per cent) believe sponsored AI answers are less trustworthy than organic responses.

AI has reached the majority of Australians faster than almost any consumer technology before it, yet trust in the technology has not kept pace. Telsyte Principal Analyst Foad Fadaghi says advertising as a revenue model only sharpens that tension.

"If it erodes confidence in AI-generated answers, it cuts against the fundamental value proposition. That is a difficult trade-off to walk back."

The study also finds 12 per cent of Australians now identify AI tools as their primary means of finding information online, up from 5 per cent a year ago. Majority (81%) are aware of AI summaries in search results, with half indicating they would often rely on the summary without clicking through to the source.

Telsyte anticipates these shifts will pressure search, publishing and digital marketing models as AI summaries and agentic search experiences become more common.

For a market where Google remains the dominant search entry point, the implications for advertisers and publishers are immediate. E-commerce and retail sites are primed to retool content for machine consumption as AI agents increasingly guide product discovery and purchasing.

AI-native hardware finds its footing as the agent-first era takes shape

The smartphone remains the primary AI device, used by 78 per cent of AI users compared with 58 per cent accessing AI on computers. Built-in everyday features such as writing assistance, live translation and AI-assisted photo editing have made AI a natural and largely frictionless part of the smartphone experience. However, Telsyte notes that more demanding use cases – such as complex workflows, coding and locally run AI agents -continue to favour computer systems with greater processing capability.

AI on smartphones and other devices is moving beyond responding to prompts - anticipating needs, acting on context and executing tasks without being asked.

Over a quarter (27%) of Australian AI users have already used AI to complete tasks on their behalf - from product comparisons and inbox management to scheduling and online shopping - marking the early stages of agentic AI in practice. However, currently only 31 per cent said they are comfortable with AI playing a larger role in managing their everyday activities.

For anticipatory and agentic AI to work, devices need access to the personal data that makes contextual awareness possible. Australians are most comfortable granting access to calendar (32%), location (26%) and email (24%), with comfort dropping sharply for more sensitive categories including cloud storage, personal notes and payment methods - none above 12 per cent.

Willingness to delegate to AI comes with conditions. Nearly two in five (39%) would allow AI to complete tasks provided they approve the final step, rising to 66 per cent among daily users. Privacy (62%), account security (59%) and fear of AI making mistakes (49%) are the primary reasons full autonomy currently remains off the table.

Despite the breadth of adoption, AI capability is not yet a primary hardware purchase driver. Only one in three Australians say their next smartphone or computer must include advanced AI features. Fundamental device attributes such as battery life and performance remain the dominant purchasing considerations, reflecting the market currently dominated by cloud-based AI services.

Two in five AI users (41%) are interested in devices from AI-native companies such as OpenAI, Anthropic or xAI, rising to 66 per cent among daily users - marking an early appetite for purpose-built AI hardware. Around one in ten are already running AI agents on a dedicated device, and among those who chose a computer for this purpose, more than 40 per cent opted for Apple silicon, a share considerably above Mac's overall market share in Australian households.

"Despite the anticipation around AI-native hardware, existing form factors like smartphones and wearables are where mass AI adoption will happen," says Telsyte Senior Analyst Alvin Lee.

Cost-of-living crunch meets AI boom as 8 million gig workers work smarter

The study found the gig and sharing economy market has grown 65 per cent from 2024 to nearly 8 million Australians in 2026, at a time when 58 per cent of Australians say they feel more financially stretched than a year ago.

The growth is more concentrated in content creation and software programming, two areas where AI tools have materially lowered the barrier to entry and expanded individual output capacity.

AI is also playing a central role in how this workforce operates. The study found 75 per cent of gig and independent workers use AI tools at least weekly, well above the 66 per cent average across the broader user population.

Three in five (61%) say AI has enabled them to accomplish tasks previously beyond their reach, a result Telsyte regards as evidence of AI's role as a genuine enabler of economic participation for this segment.

Telsyte notes, however, that two-thirds of gig workers describe these earnings as supplementary rather than primary income, a distinction that is important context when assessing AI's net impact on household financial security.

For further information on the study or media enquiries contact:

Foad Fadaghi
Managing Director
Tel: 1800 313 142
Email: ffadaghi@telsyte.com.au

Alvin Lee
Senior Analyst
Tel: 1800 313 142
Email: alee@telsyte.com.au


The Telsyte Australian Artificial Intelligence Study 2026 is a comprehensive study which provides subscribers with:

  • The state of the Australian Artificial Intelligence market, including adoption trends across standalone AI services and device-integrated AI

  • Uptake, intention and detailed analysis of leading AI services. Over 40 top services measured

  • Usage intensity analysis across daily, weekly and monthly users

  • Consumer attitudes toward AI advertising, data privacy and trust, and others in relation to AI

  • Analysis of AI search behaviour and its implications

  • Insights into agentic AI adoption, task delegation behaviour, personal data access preferences and appetite for AI-native hardware

  • The state of Australia’s gig and sharing economy market and participant trends

In preparing this study, Telsyte used:

  • An online survey conducted between April and May 2026 with a representative sample of 2,023 respondents, 16 years and older.

  • Interviews conducted with executives from hardware manufacturers and content providers.

  • Financial reports released by service providers and hardware manufacturers.

  • On-going monitoring of local and global market trends.

Editor’s note:

  • Telsyte’s measure of AI adoption include dedicated services and AI features integrated directly into devices. Device-integrated AI refer to artificial intelligence capabilities built directly into consumer devices. Examples include Apple Intelligence, Samsung Galaxy AI, Gemini on Google Pixel devices, Moto AI and Oppo AI.

  • Apple has officially opened Apple CarPlay to third-party conversational AI assistants with its iOS 26.4 release, with ChatGPT and Perplexity already available and others expected to follow. Google's Gemini is already integrated into Android Auto, while Grok is available in newer Tesla models.

  • Examples of proactive and anticipatory on-device AI features include recognising a friend's message about holiday photos and opening the camera roll directly, or nudging a user toward the calendar while composing a meeting note, consolidate notifications, messages, emails, travel bookings and personal habits into proactive daily briefs. Example of more advanced agentic features such as: a prompt to "book a taxi to the airport" sees AI open the app, fill the details and present the confirmation for a single tap of approval.

  • Gig and sharing economy work is defined by Telsyte as income-generating activities outside traditional employment, spanning platform-based gig work, freelancing, digital content creation, small business activity and asset-sharing income. This market represents individuals leveraging digital platforms, skills or assets for flexible income generation.


About Telsyte

Telsyte is Australia’s leading emerging technology analyst firm. Telsyte analysts deliver market research, insights and advisory into enterprise and consumer technologies. Telsyte is an independent business unit of DXC Technology. For more information visit www.telsyte.com.au


The material in this article is copyright protected and not intended to be altered, copied, distributed or used for any commercial or non-commercial purpose, except for news reporting, comment, criticism, teaching and scholarship.
Generative AI fuels Australia's booming IaaS market

Hyperscalers continue to dominate

SYDNEY, AUSTRALIA – Cloud applications and generative AI are the key drivers of Australia's soaring Infrastructure as a Service (IaaS) market, a new report from Telsyte, an Australian emerging technology analyst firm, reveals.

The report, titled Telsyte Australian Hyperscale Cloud Market Study 2024, shows that Australian organisations spent $4.4 billion on cloud infrastructure in 2023, a remarkable 25 per cent increase from the previous year.

The report also highlights the continued dominance of hyperscaler cloud providers, which accounted for an estimated 90 per cent of the IaaS market in 2023.

Telsyte predicts that the total IaaS market in Australia will reach $8B in revenue by 2027, propelled by growing cloud spending. Nearly half (40%) of Australian organisations plan to boost their cloud spending by 20 to 70 per cent in 2024.


Microsoft, through its partnership with OpenAI, is the leading Generation AI technology provider in Australia, with a solid presence in cloud services and productivity tools.

Generative AI, which can create novel content such as text, images, code, and music, is mainly delivered as a cloud service and fits well with most cloud applications. Natural language processing, code generation and reviews, and other use cases can be powered by cloud services.

Telsyte's research also shows that improved data analysis and insights are the top benefits that organisations expect from Gen AI.

In 2023, more than half (55%) of Australian organisations had already tried or implemented some form of Generative AI.

Cloud adoption high, but not yet mature

Cloud adoption and spending are high, but Australian IT leaders still face security and governance issues.

The study finds that cloud demand is high, with three out of four organisations considering private and public options, and only one in ten using public cloud services for less than two years.

Telsyte's cloud maturity index indicates that most of the market (71%) is shifting to more production workloads in the cloud, following the initial adoption phase.

A key finding of the study is that business units are now pushing for cloud adoption for their workloads. This is the main driver of cloud adoption, as business units do not want to wait for in-house IT to provide the infrastructure they need.

Cloud benefits such as access to new technologies and faster time to market are among the top five reasons for adoption.

Cloud challenges persist

Cloud is bringing many operational advantages to Australian organisations, but Telsyte research finds that almost all (97%) have at least one challenge with cloud.

The biggest challenges are "shadow" cloud, where business units buy cloud services without IT oversight; security; cost; and lock-in.

There is an opportunity for cloud consolidation, as two-thirds of Australian organisations use two to three different clouds, and a high 27 per cent use four to seven.

"Australian organisations have been early adopters of cloud, but in 2024 we expect to see more improvements in how cloud is used, with more maturity, more app development, and more focus on consolidation," says Telsyte Managing Director, Foad Fadaghi.

Cloud native apps gaining traction

The study shows that virtual servers are the most common IaaS application, but new areas such as serverless compute and storage are gaining popularity.

Infrastructure-as-Code (IaC), or deploying cloud infrastructure with code-level consistency and automation, is attracting high interest.

"The public clouds have enabled a new era of service automation for Australian enterprises, and there is a range of tools in use or being tested for Infrastructure-as-Code," Fadaghi says.

IaC is expected to be crucial for Generative AI deployments.

Hybrid cloud here to stay, skills needed

Telsyte's hybrid cloud research has been tracking adoption for eight years and shows that hybrid cloud is now mainstream in Australia, with eight in 10 organisations either testing or using it. Only 8 per cent have no plans for hybrid.

The preferred hybrid architecture is mainly cloud to on-premises, with cloud "bursting" also in use.

Telsyte's study also finds that there is a skills gap in Australia, with cloud networking skills in high demand and traditional database and security skills lacking in cloud.

For further information on the study or media enquiries contact:

Alvin Lee
Senior Analyst
Tel: 1800 313 142
Email: alee@telsyte.com.au

Foad Fadaghi
Managing Director
Tel: 1800 313 142
Email: ffadaghi@telsyte.com.au

The Telsyte Australian Hyperscale Cloud Market Study 2024 is a comprehensive study which provides subscribers with:

  • Market sizing and forecasts of the Australian cloud infrastructure services market

  • Analysis of market share and hyperscale performance

  • End-user trends in cloud computing

  • Strategic analysis of market opportunities for cloud infrastructure and MSPs

Telsyte’s study also includes profiles of the leading cloud vendors

  • Hyperscale profile: Amazon Web Services

  • Hyperscale profile: Google Cloud

  • Hyperscale profile: Microsoft Azure

  • Hyperscale profile: IBM Cloud

  • Hyperscale profile: Alibaba Cloud

  • Hyperscale profile: Oracle

  • Where VMware fits into the hyperscale clouds

  • Tier-2 clouds challenge hyperscalers: Telsyte forecast the rise of tier-2 clouds 3+ years ago. They offer low-cost scalability and growing range of hyperscaler features

 In preparing this study, Telsyte used:

  • An online survey of 200 IT decision makers across Australian organisations with 20 or more employees. More than half of respondents were from large organisations (>200 employees)

  • Annual reports released by market participants

  • Interviews and discussions with cloud providers, third party service providers and carriers

  • On-going monitoring of local and global market trends

About Telsyte

Telsyte is Australia’s leading emerging technology analyst firm. Telsyte analysts deliver market research, insights and advisory into enterprise and consumer technologies. Telsyte is an independent business unit of DXC Technology. For more information visit www.telsyte.com.au

The material in this article is copyright protected and not intended to be altered, copied, distributed or used for any commercial or non-commercial purpose, except for news reporting, comment, criticism, teaching and scholarship.